
Featured

5 Things to Know Today: G7 Oil Release, Pipeline Fast-Track and Ontario's N1 Deadline (Oct. 3)

  Canadian Money Brief • Saturday, October 3, 2026 Markets are closed for the weekend, so here is what moved on Friday and what it means for your wallet as the week turns. Five things worth knowing today. 1. The G7 Is Releasing 100 Million Barrels of Oil and Fuel G7 leaders, Canada included, agreed Friday to release 100 million barrels of crude and refined products from emergency reserves over the next four months, with a front-loaded diesel release in the first 20 days. Washington had been pressing allies to act as fuel prices climbed. Oil barely budged on the news: Brent settled at US$102.25 a barrel and WTI at US$91.11, down US$1.76. Analysts noted it is not yet clear whether the 100 million barrels is new supply or the tail end of the release pledged in March. What it means for you: Diesel comes first, which matters more for freight and grocery costs than for your gas tank. With Brent still around US$100, do not count on a quick drop at the pump. 2. A Weak U.S. Jobs Report Shi...
article

Record-Breaking February: S&P 500 and Nasdaq Reach New Heights


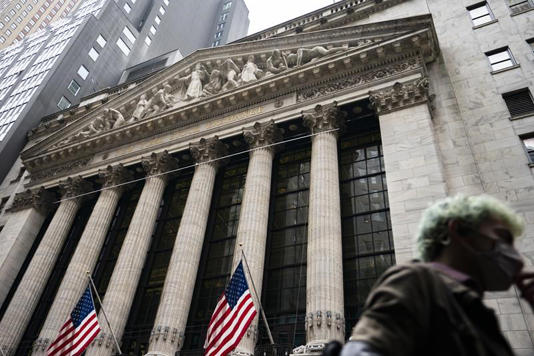
Investors witnessed an impressive rally in the stock market during February, with both the S&P 500 and Nasdaq Composite achieving remarkable milestones. Let’s delve into the details of this historic month.

S&P 500: A Stellar Performance

The S&P 500 soared to new heights, closing at 5,095.88, marking an all-time high. This gain of 0.5% on the day capped off the best February for the index since 2015. The positive momentum was fueled by several factors, including a crucial inflation reading and reassuring economic indicators.

Nasdaq Composite: Breaking Records

The Nasdaq Composite stole the spotlight, closing at 16,091.92, its highest close on record. This achievement was particularly significant as it marked the first record close for the Nasdaq since November 2021. The tech-heavy index surged 0.9% on Thursday, reflecting the robust performance of technology companies.

Inflation and Market Sentiment

The closely watched Personal Consumption Expenditures (PCE) index grew 2.4% year-over-year in January, slightly lower than the previous month’s 2.6%. The “core” PCE, the measure often emphasized by Fed Chair Jerome Powell, came in at 2.8%, down from 2.9% in the prior month. Policymakers continue to monitor inflation closely, emphasizing the need for signs of easing price pressures before committing to rate cuts.

Bitcoin’s Resilience

Meanwhile, bitcoin (BTC-USD) maintained its position above $62,000, coming close to its all-time high of $64,000. The leading digital currency’s recent rally has been unprecedented, reminiscent of the pre-“crypto winter” surge in 2022.

Earnings Outlook

As we wrap up the fourth quarter, the S&P 500 is projected to achieve 4% earnings growth compared to the same period last year. Notably, the outlook for earnings growth in the current quarter remains positive, defying the usual downward revisions seen during this time.

In summary, February 2024 will be remembered as a month of remarkable achievements in the stock market. Investors remain cautiously optimistic, closely monitoring economic indicators and inflation trends. As we move forward, the resilience of both the S&P 500 and Nasdaq Composite provides hope for continued growth.


Comments